Published
Author

Callum
Categories
AEO & GEO


Ready to take it a step further?
Let's start talking about your project or idea and find out how Creato can help your business grow.
A mortgage enquiry is not a settled loan. Every broker who has watched a promising conversation stall between initial discussion, documents and lender assessment knows that. A marketing report showing cheap leads can look impressive while the settlement pipeline remains thin.
The problem is often fit rather than volume. A borrower may be at an early research stage, need a service outside the broker’s scope or have misunderstood a headline about eligibility. The website should help people understand the process and decide whether to start a conversation, not imply that an online form establishes approval.
AI search adds another discovery channel to this journey. Used well, it can make a broker’s expertise and service approach easier to find. Used badly, it spreads generic promises and attracts enquiries the business cannot responsibly help. This guide covers marketing, not borrowing recommendations, credit advice or an assessment of anyone’s eligibility.
What AI visibility means for a mortgage broker
A prospective borrower might ask how to choose a broker, what questions to ask before refinancing or what information a self-employed applicant may need to discuss. An assistant may summarise general information, cite a website or mention firms. None of those events is loan approval or proof of an adviser’s suitability.
Google’s guidance on AI features connects eligibility to established SEO foundations and does not guarantee inclusion. That makes accurate, accessible content a more defensible starting point than claims that a broker can buy a permanent place in AI answers.
Treat visibility as a route to an informed conversation. Track whether the right people find the right service pages and understand the next step. A citation can be useful without producing an immediate enquiry, while an enquiry can arrive after several later searches.
Our SEO, AEO and GEO strategy guide explains the channel differences. For brokers, the practical objective is a trustworthy discovery-to-settlement journey, with marketing measurement kept distinct from credit assessment.
Choose borrower journeys your business can genuinely support
Do not begin with a plan to rank for every mortgage question. Start with the borrower groups and services your business actually supports: first-home buyers, refinancers, self-employed applicants or other clearly defined segments. Confirm scope with the people responsible for advice and compliance.
Different journeys need different content. A first-home buyer may need to understand the sequence of discussions and decisions. A refinancer may be comparing the process and potential costs of changing arrangements. A self-employed person may want to know how to prepare for a conversation without being promised that a certain document guarantees acceptance.
Build a topic map that separates education, provider comparison and contact intent. An article explaining what a broker does should not compete with ten near-identical articles. A service page should answer why a person might speak to your team and what happens next, rather than reproduce a generic home-loan glossary.
Keep geography honest. National service does not mean international authorisation. A broker operating across one country should explain that scope clearly. If you publish content relevant to another country, label its jurisdiction and have it reviewed by someone qualified to assess that context.
Answer the questions borrowers should ask about the broker
A useful website explains who provides the service, what the process involves, how the business is remunerated where relevant, and where readers can verify credentials. These details should be accurate and consistent with the firm’s approved disclosures, not improvised by a copywriter.
In Australia, Moneysmart’s guide to using a mortgage broker encourages consumers to check licensing or representative status and ask questions about a broker’s service. Use that as a reminder to make verification and practical explanations straightforward. Do not suggest every broker has access to every lender.
Explain the actual service proposition. If your team supports remote appointments nationally, describe how they work. If you offer particular language support, confirm availability. If enquiries are handled by a team rather than the person shown in a hero photograph, explain who will contact the borrower.
A clear proposition may sound less dramatic than “the best loan guaranteed”, but it is more useful. Specific, supportable information lets people compare providers without creating an expectation your business cannot substantiate.
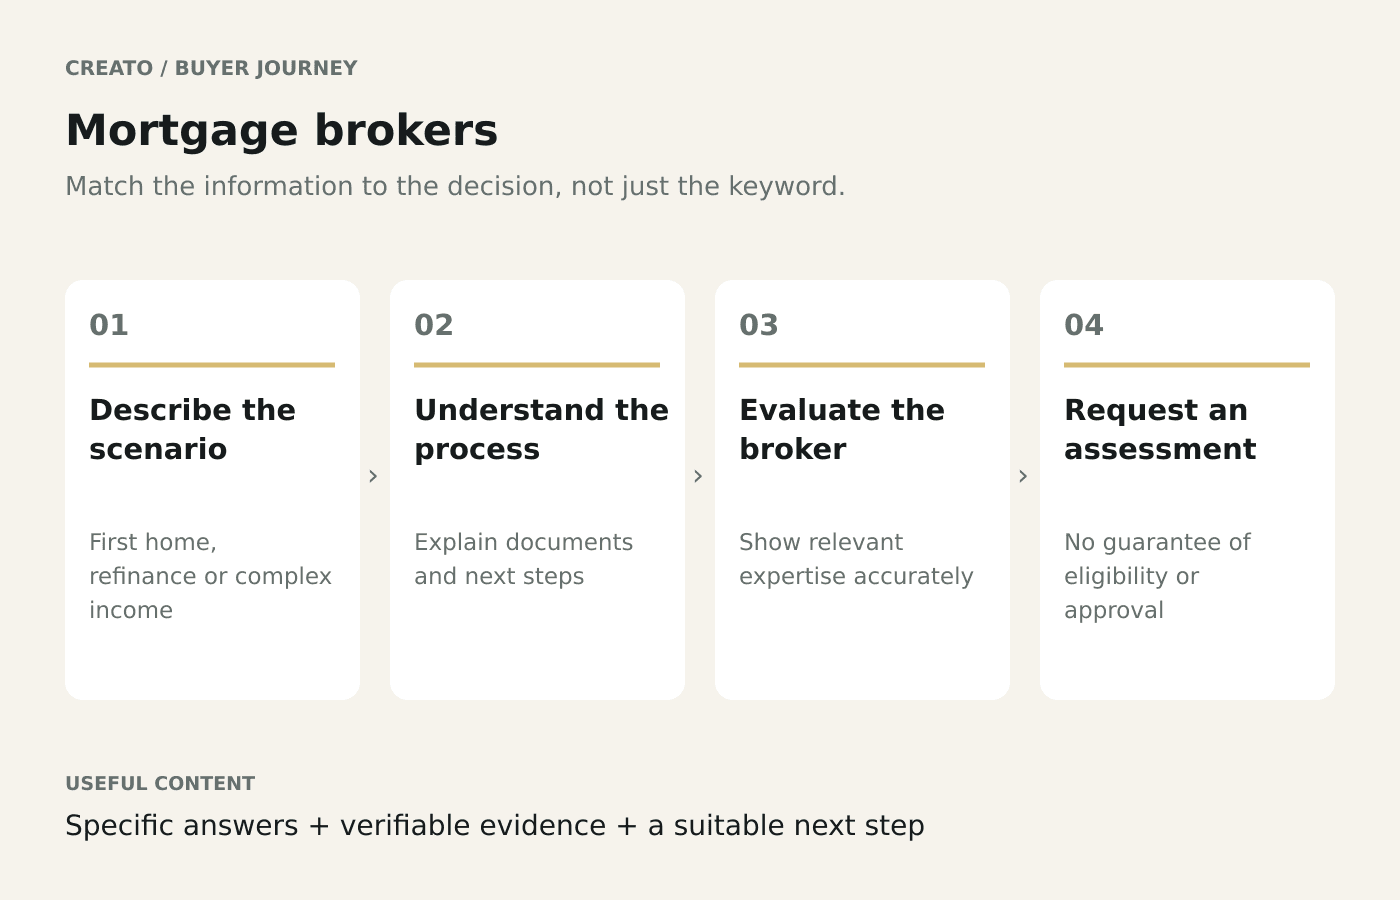
A practical content-planning framework. Real buying journeys may loop or involve several decision-makers.
Keep approval, rates and savings claims under tight control
Mortgage marketing can become misleading through implication as well as an obviously false statement. A large headline may suggest certainty while the qualifications appear far below it. A calculator may look like an assessment. A rate comparison may omit conditions that materially affect how a borrower understands it.
For Australia, ASIC’s RG 234 advertising guidance addresses advertising financial products and services, including credit, and misleading conduct. Have the appropriate professional review claims and required disclosures. This article is not a substitute for compliance advice or a complete summary of the rules.
Avoid guarantees of approval, the lowest rate or a particular saving unless the exact claim is lawful and genuinely substantiated. Do not let an AI drafting tool invent lender policies, serviceability rules, rates or comparison figures. Time-sensitive product content needs an owner, a verification source and an update process.
For international content, distinguish local processes. The US Consumer Financial Protection Bureau’s Loan Estimate comparison guidance concerns a specific disclosure framework. It should not be presented as the process Australian borrowers follow. A country label is not decorative; it changes what the reader can safely infer.
Build pages around preparation and informed comparison
Useful broker content helps people prepare for a real conversation. Explain the broad stages, questions they may want to ask and the difference between an initial discussion and later assessment. Keep any document checklist subject to the business’s current process and individual circumstances.
A self-employed borrower page, for example, can explain why a broker first needs to understand the business context and what the initial conversation covers. It should not promise that one category of paperwork secures a loan. A refinancing page can explain the topics considered without concluding that refinancing is right for every reader.
Show the limits of generic calculators. If the website uses one, explain assumptions, what the result does and does not represent, and where a person can get an individual assessment. Do not design a result screen that turns an illustrative number into a pseudo-approval.
Create distinct content only where it answers a distinct need. Replacing a town name in a page about home loans does not add expertise. A well-developed service page with useful national coverage and genuine local information is more credible than a large set of thin location variations.
Use evidence that does not expose borrowers
Trust can come from accurate credentials, real team profiles, clear process information and documented professional contributions. It does not require publishing a borrower’s financial circumstances or a dramatic settlement story.
If case studies are used, apply the firm’s permission, privacy and compliance processes. Anonymised figures can still reveal someone when combined with location, occupation and timing. Do not assume that changing a first name makes a scenario safe to publish. A fictional illustration should be identified as fictional rather than passed off as a client result.
Reviews also need context. Never invent them, pay for fabricated praise or selectively rewrite a borrower’s words to suggest an outcome they did not describe. A positive experience does not prove that another person will receive the same loan terms or result.
For original expertise, explain how the team organises communication, prepares a discussion or helps people understand the stages. Use real operational knowledge without turning the website into personalised credit advice. That distinction makes content useful while keeping professional decisions in the appropriate process.

40 qualified enquiries × settlement rate × A$1,500 contribution per settled loan. Eventual cohort settlements, not same-month; costs/clawback allowance assumed. These are assumptions, not results or benchmarks.
Make the first step simple and the sensitive step secure
A marketing form should ask only what is necessary to arrange the initial contact. Detailed income, account information, identity documents and supporting financial records should move through the firm’s approved secure workflow, not an ordinary website message box.
Describe the form accurately. “Request a call” should mean a request for contact, not an application, pre-approval or promise that a loan is available. If a booking link reserves a time, explain what that appointment is for and what the person should expect.
Test delivery from the website to the actual intake team. Check mobile usability, notifications and fallback contact details. If an external customer-management system receives enquiries, verify the handoff with approved test data and prevent those tests from appearing as genuine leads in reports.
Review analytics implementation with privacy in mind. Loan details, identity information and document contents should not leak into URL parameters, event labels or general advertising tools. Marketing measurement can follow a consented enquiry through business stages without transmitting every detail of a borrower’s circumstances.
SEO versus ads for mortgage brokers
Paid search can reach people who are actively looking for a defined service. Organic content can support education and provider comparison earlier in the journey. The useful question is how each channel contributes to appropriate, serviceable enquiries and eventual business outcomes, not which produces the largest lead count.
For ads, separate intent where it changes the proposition. A person looking for general information may not be ready to speak to a broker. Check search terms, landing-page clarity and the actual meaning of conversions. A click on a contact button is weaker evidence than a legitimate enquiry.
For SEO, start with accurate service pages, credible people and focused answers to recurring questions. Technical maintenance and content review are continuing costs. There is no universal date by which an article will rank or be cited by an AI system, so do not budget as though organic acquisition becomes free after publication.
A sensible combined strategy can use paid campaigns to test a specific proposition while building durable educational resources. Keep budget, scope and success criteria explicit. Do not scale a campaign because initial forms are cheap if the downstream enquiries repeatedly fail the business’s fit criteria.
Evaluate enquiry cohorts through to settlement
Mortgage acquisition often has a long and uneven path. Comparing this month’s marketing spend only with this month’s settlements can attribute older work to new campaigns or judge a new campaign before its enquiries have had time to progress.
Create enquiry cohorts by acquisition period and service type. Follow them through legitimate enquiry, appropriate initial conversation, later business stages and settlement where applicable. Define stages with the team rather than adopting labels that imply an assessment has occurred when it has not.
Record reasons for non-progression at a useful, privacy-conscious level. Some people are researching, some choose another provider, and some do not fit the service. Those categories point to different improvements in content, timing or process. Avoid storing unnecessary sensitive detail in marketing reports.
Keep the reporting honest about unresolved cases. A pending opportunity is not a settlement, and a settlement is not automatically the same as final retained contribution. Where remuneration or costs can change later, use the firm’s actual accounting treatment and a clearly defined measurement period.
An illustrative investment-versus-enquiry-value model
The following is hypothetical arithmetic, not a broker benchmark, commission estimate, Creato result or forecast. Assume A$3,000 marketing cost for a cohort of 40 qualified enquiries. Assume A$1,500 contribution per eventual settled loan before marketing, after assumed delivery costs and an allowance for clawback risk. Use your actual figures instead.
If 5% of the cohort eventually settles, two settlements produce A$3,000 contribution, equal to the assumed marketing cost. At 10%, four settlements produce A$6,000, leaving A$3,000 after marketing. At 20%, eight settlements produce A$12,000, leaving A$9,000. General overheads and taxes remain outside this simplified model.
Expected contribution per qualified enquiry is A$75, A$150 or A$300 respectively. These are not recommended acquisition bids. Cash timing, uncertainty, the accuracy of the cost allowance and available service capacity all matter. The cohort may settle over several months, so the chart must not be described as monthly revenue.
Be conservative about future trail income or repeat business. Do not use speculative lifetime value to excuse a campaign that has not produced suitable enquiries. A model is most useful when it shows which assumptions drive the decision and what would make the investment fail, not only the attractive scenario.
Build a dashboard that can challenge the marketing story
Report the full picture: relevant visibility, visits, legitimate enquiries, qualified conversations and later outcomes. Separate branded and non-branded discovery where the data supports it. Distinguish known attribution from a best-effort interpretation, particularly when a person returns through multiple channels.
Ask an optional question about how the person found the business. Combine the answer with privacy-appropriate analytics rather than treating either as perfect. Someone may see an AI answer, ask a friend and then search your name. A single source label cannot always represent that history.
For AI checks, use realistic prompts for your services and markets, record the response and check cited destinations. Keep the sample stable enough to compare. Do not claim market-wide dominance from a few selected answers, and do not interpret one disappearance as proof the entire strategy failed.
Our monthly SEO reporting guide explains the principle: useful reporting should change a decision. If a metric cannot help you improve fit, conversion, service delivery or investment allocation, it may not belong at the top of the dashboard.
Prioritise a manageable first phase
Begin with a factual audit of the service pages, credentials, claims and enquiry handoff. Identify stale rates or unsupported language and route them for review. Establish the target borrower journeys and the business’s capacity to respond before increasing traffic.
Then strengthen the core pages and publish a small set of distinct educational resources. Add helpful process diagrams, verify links and test the mobile experience. Assign an owner to every time-sensitive page. Build the review process into the publishing plan rather than treating it as an optional final check.
As evidence accumulates, compare cohort quality and progression. Improve the weakest stage instead of automatically buying more leads. If the proposition is attracting the wrong enquiries, clarify it. If the handoff is slow, fix it. If visibility is limited, inspect relevance and technical foundations.
Creato’s SEO services and AEO and GEO services can help connect those pieces. A national or international strategy should reflect your authorised service reach, with country-specific content where required.
Make your business easier to understand, not harder to question
The best mortgage-broker website helps people ask better questions. It explains what the business does, makes credentials verifiable and offers a clear next step without disguising uncertainty as a guarantee.
If you want to improve the path from discovery to appropriate enquiries, talk to Creato about your mortgage-broker website and search strategy. Start with your actual service model, current conversion stages and the evidence available, rather than a promise of instant AI rankings.
For more implementation guidance, visit the Creato blog and our technical AEO and GEO guide. Search visibility is valuable when it supports informed conversations and a trustworthy process, not simply a larger pile of unqualified forms.


